
Sinking fund categories for everyday expenses are essential for smart financial planning. They help you save consistently for various costs, preventing budget shocks. Incorporating these funds ensures you’re ready for any financial surprises that may pop up.
Understanding different categories can simplify your saving process. Each category serves a unique purpose, making it easier to allocate funds for specific needs. Whether it’s for repairs or vacations, sinking funds can enhance your budgeting skills.
Looking to improve your financial health? Keep reading to discover how sinking fund categories can transform your everyday expenses!
Understanding Sinking Funds
Understanding sinking funds is crucial for managing your finances effectively. A sinking fund is a special savings account where you set aside money for specific future expenses. This method ensures that you have enough savings to cover costs without straining your budget when the time comes.
By planning for expenses like vacations, car repairs, or holiday gifts, you can avoid financial stress. Every month, you contribute a small amount to your sinking fund, making these larger expenses more manageable. This approach helps you save consistently and reach your financial goals.
Sinking funds work well for everyday expenses because they bring clarity to your spending. You know exactly how much to save and when you’ll need it. With this knowledge, you can make better decisions about your money and reduce the chance of unexpected bills affecting your budget.
Benefits of Sinking Funds
There are many benefits of sinking funds that can help you manage your everyday expenses. One major advantage is avoiding financial surprises. By saving for specific costs ahead of time, you can prevent stress when bills come due. With sinking funds, you can plan and know exactly what each expense will require.
Another benefit is improving your budgeting skills. When you use sinking funds, you learn to allocate your money wisely. This method encourages you to consider your expenses regularly and adjust your savings as needed. It may also help you recognize areas where you can cut back to save more.
Sinking funds also allow for greater flexibility and peace of mind. Knowing you have money set aside for certain expenses means you can spend without worry. It provides a clear picture of your finances, helping you make better decisions and enjoy your spending more, whether for fun or necessities.
Types of Sinking Fund Categories
Understanding the types of sinking fund categories is essential for effective budgeting. Common categories include emergency funds, vehicle maintenance, and holiday expenses. An emergency fund helps cover unexpected costs like medical bills or urgent repairs. Vehicle maintenance ensures you are prepared for expenses like oil changes or new tires.
Another important category is vacation funds. By setting money aside for trips, you can enjoy traveling without financial stress. Creating separate categories for personal expenses, such as hobbies or gifts, allows for better control of spending while encouraging you to enjoy life.
It’s also helpful to have a category for home repairs. Whether you need to fix a leaky roof or repaint a room, having savings designated for these needs will help you manage large expenses easily. By recognizing various sinking fund categories, you will enhance your ability to budget and save for what truly matters in your life.
How to Create a Sinking Fund
Creating a sinking fund starts with identifying your goals. Begin by listing the specific expenses you want to save for, like vacations, car repairs, or birthday gifts. This step allows you to see what categories matter most to you and how much you will need for each.
Next, calculate how much money you need to save monthly for each category. Divide the total amount needed by the number of months you have until the expense is due. For example, if you want to save $600 for a vacation in a year, you should put away $50 each month.
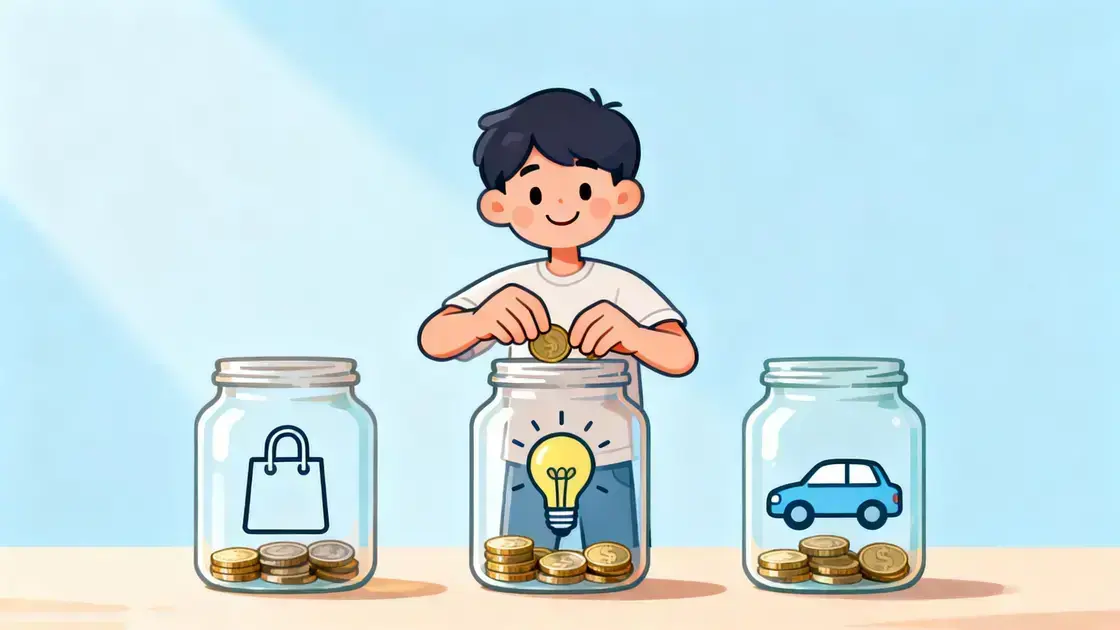
Finally, choose a separate account or jar to keep your sinking fund money. Having it in a dedicated space helps you avoid spending it accidentally. Regularly review your sinking funds to make sure you’re on track and adjust your savings if necessary. This way, you’ll always be prepared for your upcoming expenses!
Best Practices for Sinking Funds
To get the most out of your sinking funds, it’s important to set clear goals for each category. Make sure your savings targets are specific and realistic. For example, if you want to save for a vacation, decide how much you need and by when. This practice keeps you motivated and on track to reach your financial goals.
Another best practice is to review your sinking funds regularly. Check if you are meeting your saving goals each month and adjust your contributions if needed. Life changes, and so do expenses, so staying flexible is key. Regular reviews help you remain aware of your financial situation and make necessary adjustments.
Lastly, automate your savings whenever possible. Set up automatic transfers to your sinking fund each payday. This strategy makes saving easier and ensures that you consistently contribute to your funds without having to think about it. Automation can help you build your savings effortlessly, making it easier to enjoy the benefits when the time comes.
Common Mistakes to Avoid
One common mistake to avoid when creating sinking funds is underestimating your expenses. It’s easy to think that you won’t need as much money for certain categories. For instance, skipping small savings can add up over time. Always budget a little extra for each category to ensure you are covered when expenses arise.
Another mistake is not keeping your sinking funds separate from your regular savings. Mixing these funds can lead to confusion and unintentional spending. It’s best to use different accounts or clear jars labeled for each category. This practice helps you stay organized and aware of how much you have saved for each purpose.
Finally, be cautious about not having enough flexibility in your sinking funds. Life can be unpredictable, and your priorities may change. If your financial situation shifts or you have unexpected expenses, make sure to adjust your savings plan. Staying adaptable will help you manage your sinking funds more effectively over time.
Tips for Managing Your Sinking Funds
Managing your sinking funds effectively starts with keeping accurate records. Use a budgeting app or a simple spreadsheet to track your contributions and expenses. Regularly updating these records helps you see your progress and makes it easier to adjust your savings as needed. This way, you’ll always know where you stand with your funds.
Another important tip is to review your sinking funds at least once a month. Check if you’re meeting your savings targets and assess if any changes are necessary. If you find that you can save a little more or need to rearrange categories, make those adjustments. This ongoing check-in keeps your goals fresh and relevant.
Lastly, celebrate your progress to keep yourself motivated. When you reach a savings milestone, treat yourself to something small or enjoyable. Recognizing your hard work with rewards can help you stay engaged and excited about saving. Keeping your sinking funds fun and rewarding encourages you to continue managing them well.
Adjusting Your Sinking Fund Categories
Adjusting your sinking fund categories is an important part of effective money management. As your financial situation changes, so can your saving needs. Take time to review your categories regularly and think about whether they still align with your current goals. For example, if you plan a big trip, you might want to increase your vacation fund while decreasing other savings temporarily.
It’s also helpful to add new categories when necessary. Life events, such as buying a new car or planning home renovations, may require you to set up additional sinking funds. By adding these categories, you can ensure that you are financially prepared for upcoming expenses without scrambling for cash later.
Finally, don’t be afraid to eliminate categories that are no longer relevant. If you find that you no longer need a specific fund or have consistently over-saved for that purpose, consider cutting it out. This helps you focus on what truly matters and keeps your financial plan streamlined and effective.